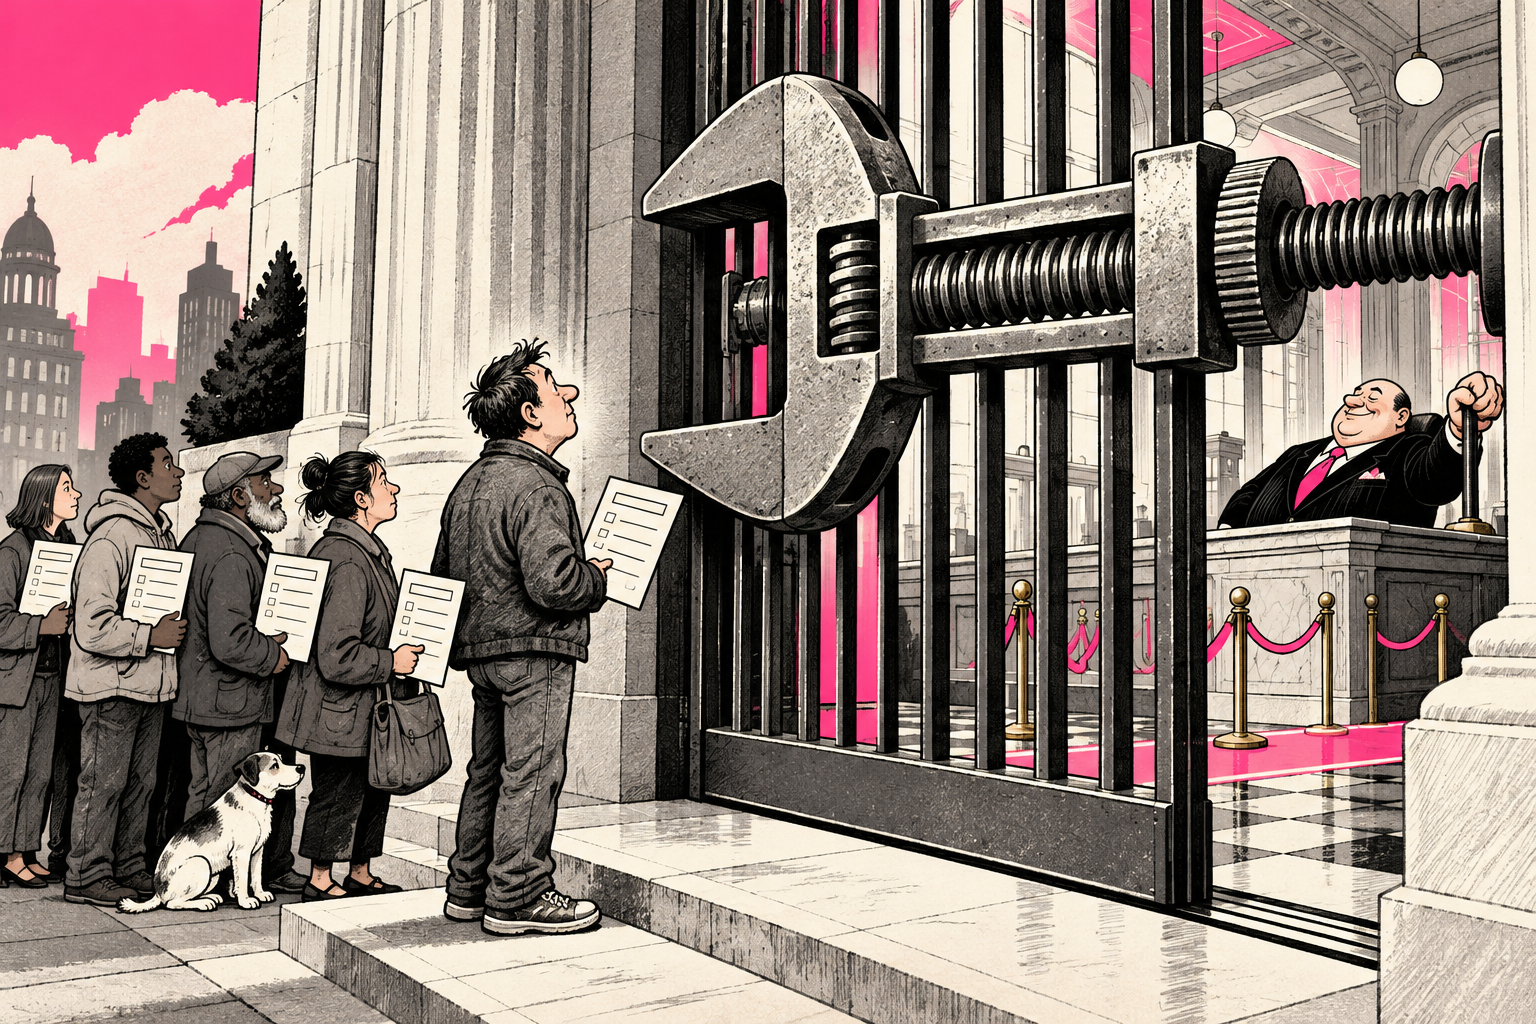
A checking account should not require a successful audition for the bank’s preferred version of respectable society. The overdraft fee is already doing quite enough judging.
On October 14, the Office of the Comptroller of the Currency released findings on the nine largest national banks it supervises. The OCC says broad reputation-risk policies and subjective standards disadvantaged some customers or lawful businesses during the period it examined.
Reuters reports that the regulator did not announce penalties and that banks have defended account decisions as responses to legal, financial, or reputational risks rather than politics. The report’s findings and the banks’ position should be distinguished from a court’s determination about any individual account closure.
Fair Access Should Be A Consistent Principle
There is a sound liberal argument for limiting arbitrary financial exclusion. An ordinary person’s ability to receive income, pay bills, or operate a lawful business should not depend on passing an unexplained cultural suitability test.
That principle does not change when the customer’s views are conservative. Rights and fair procedures should not be awarded according to whether we would enjoy sharing a dinner table.
It also does not mean banks must disregard actual financial risk or legal obligations. The useful task is to distinguish relevant, objective criteria from vague judgments that cannot be explained or challenged.
A phrase such as reputation risk can describe a real business concern. It can also become a container large enough to hold almost anything the institution prefers not to discuss.
When a decision has serious consequences, the explanation should be more substantial than the financial equivalent of we just did not feel a connection.
Regulators should ask how criteria are defined, how decisions are documented, and whether customers have practical ways to correct errors or obtain appropriate review. Those are questions about administration and evidence, not an invitation to make every denial a political scandal.
Follow The Rules Beyond The Famous Complaint
The temptation in a political argument is to focus on the prominent person who says a bank treated them badly. That may generate a headline. It should not become the entire standard for financial fairness.
The less famous customer deserves attention too. A small business or household can suffer real disruption without possessing the audience necessary to turn its complaint into a national controversy.
If the OCC’s concerns identify genuine weaknesses, the response should improve clear and consistent practices for everyone. It should not merely create a better complaint channel for people whose political connections are especially well developed.
The same scrutiny should apply to regulatory overreach. Officials should not pressure a bank to serve a favored customer by ignoring a legitimate risk. Fair access and sound banking need to be pursued together, not traded against each other according to which argument is convenient that week.
Public reporting should explain the scope of the findings and the actions actually taken. A new report is not automatically a fine, and criticism of a policy is not proof that every affected decision was unlawful.
My preference is a system in which lawful customers receive intelligible standards and banks remain answerable for how they apply them. That requires stronger procedures and useful evidence, not just a louder declaration of fairness.
The current report gives policymakers a concrete set of claims to examine. The next step is to assess the findings, hear the institutions’ responses, and show how any changes improve ordinary access.
Banking should have risk controls. It should not have a velvet rope whose entrance policy changes depending on who is complaining outside.